I once bought a $300 espresso machine at midnight because a video made it look life-changing. I do not drink espresso. It sat on my counter for a year before I sold it for $80. That was my rock bottom, and it taught me something: I did not have a discipline problem, I had a system problem. Once I built systems that slowed me down, the impulse buying mostly stopped on its own.
Why Willpower Always Loses to a Good System
Impulse spending is brain chemistry. Your brain releases dopamine at the moment of purchase, not when the package arrives, which is why the thrill fades before the box is open. Willpower depletes over the day, and that is exactly when the shopping apps come out.
Mindful spending is not never buying fun things. It is inserting a pause between want and buy so your calmer self gets a vote. Every habit below adds friction to the purchase path. None require willpower in the moment, because the system already decided.
- 24-hour waiting rule for anything over $30
- Unsave your cards from every shopping site and app
- One weekly cash envelope for fun money, no exceptions
- A no-spend weekend once a month to reset your baseline
1. Name Your Spending Triggers, Then Avoid the Worst One
Every impulsive spender has one or two wallet-opening situations: boredom scrolling at 11 p.m., stress after a hard day, sale emails, a friend’s recommendation. For one week, note what you bought on impulse and what you felt right before. A pattern jumps out fast.
Do not fix every trigger. Neutralize the worst one. Late-night scrolling? Charge your phone in the kitchen. Sale emails? Unsubscribe today. Removing one trigger can cut impulse spending in half, and it costs nothing.
2. Put Everything on a 24-Hour List Before You Buy It
Keep a “want list” in your phone’s notes. Every non-essential purchase goes on it with the date, and you wait 24 hours. If you still want it tomorrow, buy it. About 80 percent of the time, you will wonder what you were thinking.
The list stops the instant purchase and reveals your patterns. After a month, read what you never bought: hundreds of dollars kept. The few things you buy after waiting will be things you actually enjoy.
3. Set a Personal Price Threshold (Mine Is $50)
Pick your line in the sand. Below it, buy freely. Above it, the 24-hour rule kicks in. Scale the wait with the price: 72 hours over $200, a full week over $500. Bigger purchase, longer pause.
The threshold removes the in-the-moment decision. You set the rule on a calm Sunday, so your stressed Friday-night self does not have to think.
4. Unsubscribe From Every Marketing Email Today
Every sale email is a trigger engineered to make you buy things you were not seeking. Spend twenty minutes unsubscribing from all of them. Search your inbox for “unsubscribe” and work the list. Highest-return twenty minutes in personal finance.
You will not miss a single deal that matters. Anything you truly need, you will go find. A quiet inbox is worth more than every coupon code combined.
5. Unsave Your Cards and Delete Shopping Apps
One-click checkout removes the moment you might change your mind. Put it back. Delete saved cards from every site, remove shopping apps, turn off payment autofill. Now every purchase means finding your wallet and typing sixteen digits.
That two-minute hassle is the whole point. Most impulse buys die on the walk to get your wallet. You are not banning shopping, just making it slightly inconvenient, which stops the purchases you never wanted.
6. Use the “Cost in Hours” Test
Convert prices into work hours. Those $120 shoes at $15 an hour are eight hours of your life. A $40 takeout habit three times a week is over $6,000 a year. Suddenly the purchase has a weight the price tag hides.
This does not say never buy. It says buy with open eyes. Some things are worth eight hours. Most impulse buys are not. Tape your hourly number inside your wallet if you need the reminder.
7. Shop With a Written List or Don’t Go
Wandering a store or site without a list is how $40 grocery trips become $120 ones. Write down exactly what you need before you shop. Buy the list. Anything else goes on the 24-hour list.
Retailers design stores to trigger unplanned purchases: end caps, checkout candy, “customers also bought.” A list is armor against all of it.
8. Carry a Weekly Cash Envelope for Fun Money
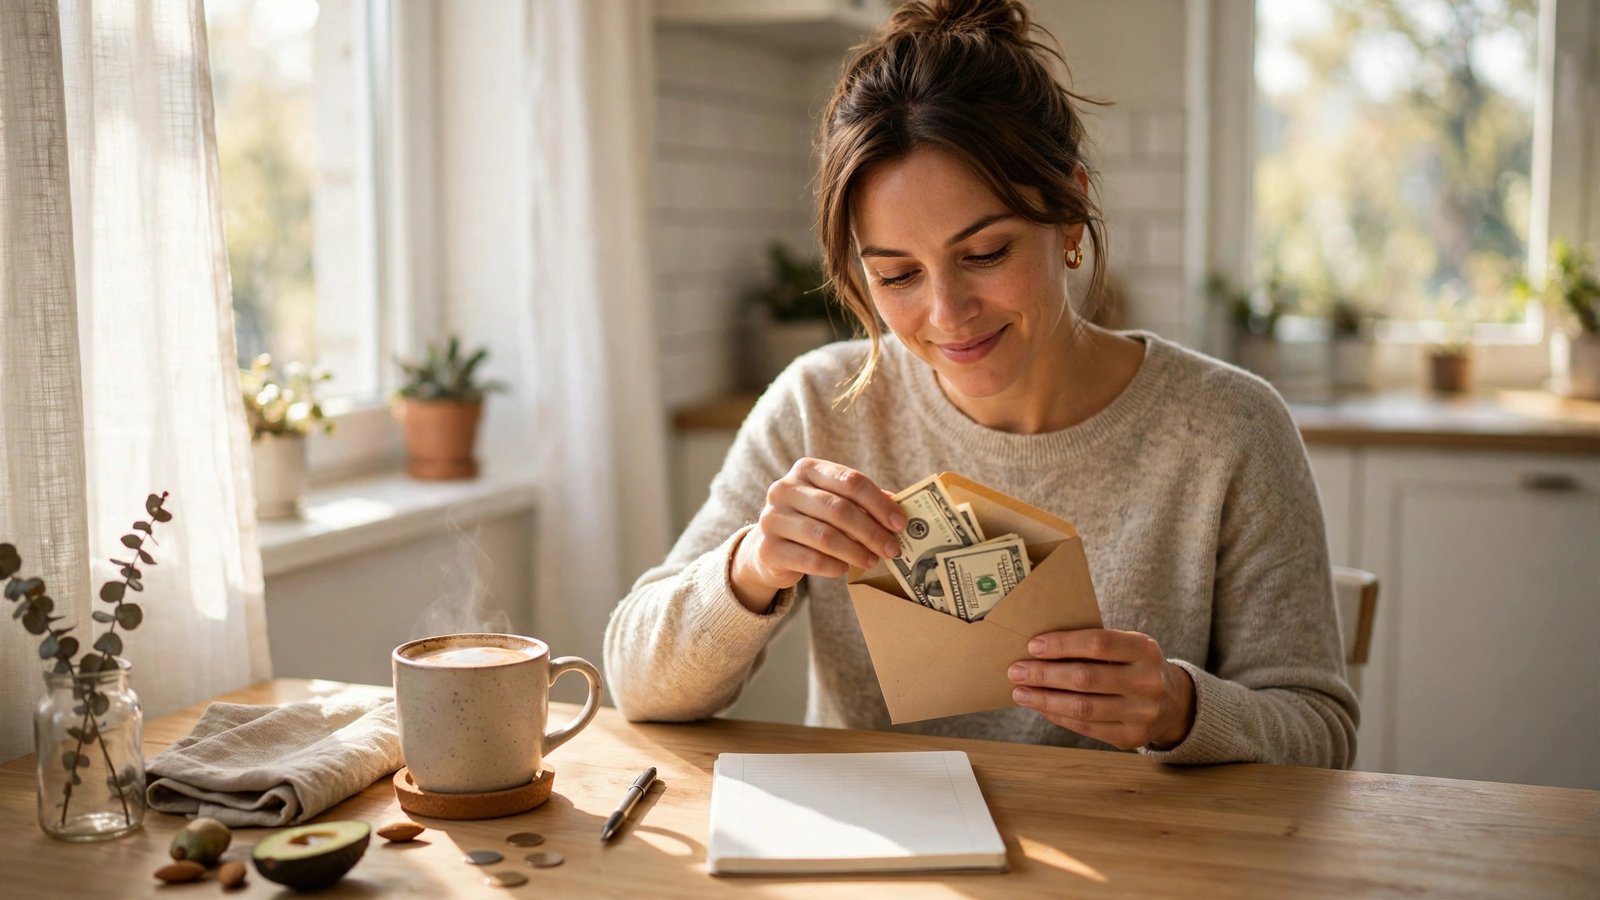
Pick a weekly fun-money amount, mine is $60, and put it in a cash envelope every Monday. Coffee, snacks, random wants all come from the envelope. Empty means done until next Monday. No topping up.
Cash is physical, and watching the envelope thin out hurts in a useful way. You naturally prioritize: is this $12 lunch worth a third of the week’s fun? Some weeks cash is left over, which feels like winning.
9. Build a Wish List Fund Instead of Buying Now
For things you genuinely want, create a savings bucket with the item’s name and feed it monthly. A $600 bike at $75 a month is yours in eight months, bought with zero guilt.
This turns impulse into intention. You still get the thing, but only after the excitement survives the wait. Half the time you will redirect the fund to something you want more.
10. Tell One Friend Your Goal (Accountability Works)
Tell one trusted friend your real goal: “I am trying to save $200 a month.” Then make a deal: before any purchase over your threshold, you text them first. Not for permission, just to say it out loud.
Saying “I am about to buy a $180 jacket I do not need” kills most purchases dead. The friend need not judge. Typing the message is the intervention. No friend available? Write it to yourself in your notes app.
11. Do a No-Spend Weekend Once a Month
Pick one weekend monthly with zero spending: no eating out, no shopping, no paid entertainment. Plan free activities in advance: a hike, the library, a cook-at-home movie night. The first feels strange. By the third, it feels like a reset.
A typical no-spend weekend saves me $100 to $150, or up to $1,800 a year. The deeper payoff: learning weekends can be full without spending, which quietly reduces spending on all the other weekends too.
12. Review Your Last 30 Days of Spending Every Sunday
Ten minutes a week scrolling your transactions. Not to punish yourself, just to look. You will spot the forgotten $14 subscription, the three takeout orders, the regret buy. Awareness alone changes behavior.
Most banking apps categorize spending automatically. I do mine Sunday mornings with coffee and note one-line surprises. After two months, my impulse spending halved without me “trying” to cut anything.
13. Return Something Every Month (Guilt-Free)
Returns are part of the system, not failure. Keep receipts for a month; if you have not used something or the thrill wore off, take it back. Stores expect this.
Do it before the return window closes. Put new purchases in one spot and set a day-25 phone reminder. Untouched by then? It goes back. This also makes you a more careful buyer over time.
14. Replace the Habit, Don’t Just Ban It
Impulse shopping fills a need: boredom, stress, loneliness, the craving for a treat. Banning the shopping without replacing the need builds pressure until you crack. Replace it deliberately instead.
I replaced evening scrolling with library ebooks, free and endless. My spending urge was really a novelty urge, and books deliver novelty free. Find what your spending feeds, feed it another way, and the grip loosens.
Mistakes That Restart the Impulse Cycle
The biggest mistake is the all-or-nothing ban: “I will never buy anything fun again.” It lasts two weeks, then you rebel-buy something huge. Sustainable beats strict. The cash envelope exists so fun spending has a legal, limited home.
Second is the shame spiral: one slip, then “I already failed, why bother.” One slip is data, not doom. Log it, note the trigger, continue. Winners are not people who never slip. They are people who slip and keep going.
A Simple Weekly Money Check-In
Every Sunday, ten minutes: glance at transactions and note surprises, reset the cash envelope, delete dead items from your want list, check your wish list fund balance and smile at the progress.
Ten minutes a week keeps your money conscious. I have done this for over a year, and it is the one habit I would keep if I dropped everything else. Conscious money behaves. Unconscious money evaporates.
Conclusion
That espresso machine taught me the truth I needed: I would never out-willpower my impulses, but I could out-system them. A waiting list, deleted apps, a cash envelope, and a Sunday check-in did what years of resolutions never could. Build the friction, and mindful spending follows.