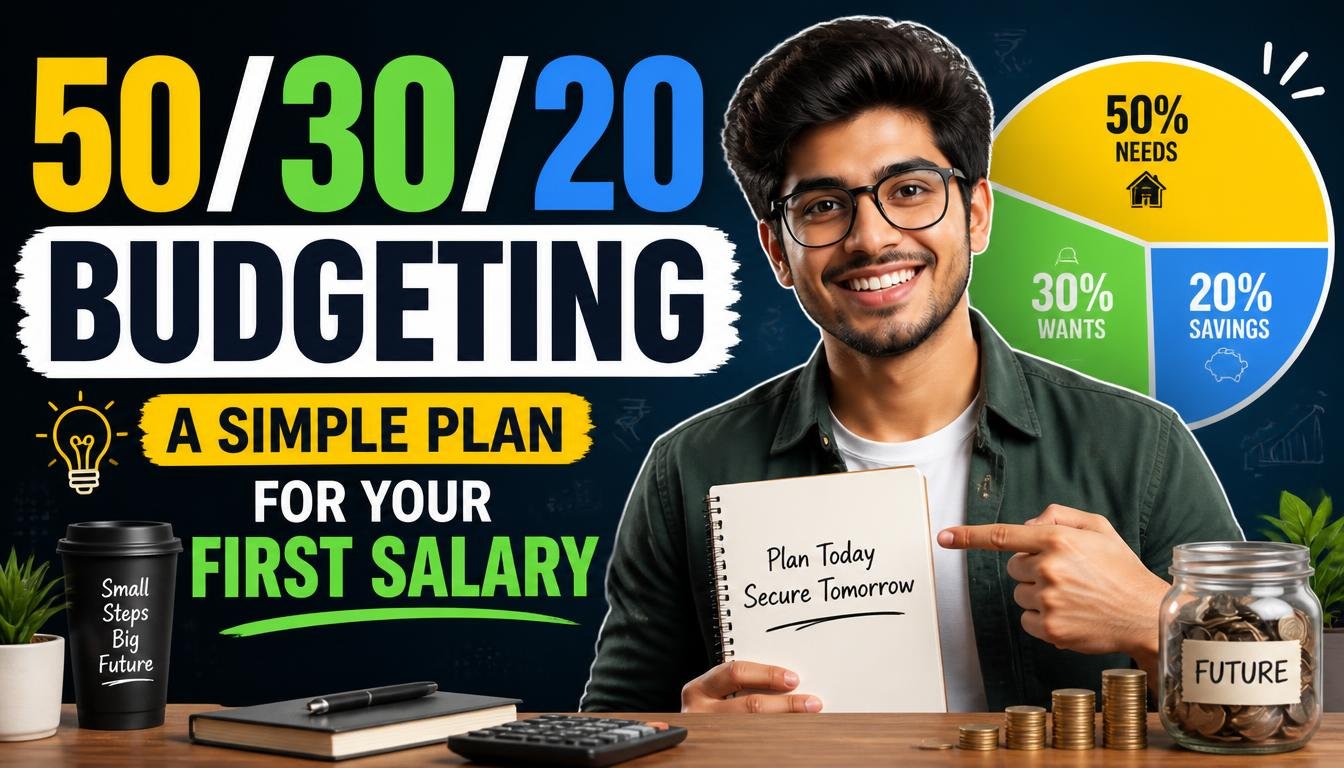
50/30/20 budgeting sounded like another internet rule to me until my first real paycheck vanished in eleven days. Rent, takeout, a new jacket, and suddenly I was doing sad math at 2 a.m. I needed a system so simple I could not mess it up. This one splits every paycheck into three buckets, needs, wants, and savings, and it finally made my money behave.
1. Start With Your Take-Home Pay, Not Your Salary
Your salary is a fantasy number. The only number that matters is what lands in your checking account after taxes, insurance, and retirement contributions. I budgeted off my gross salary for three months and wondered why I was always short. The fix took five minutes: I opened my pay stub, found the net pay line, and rebuilt everything from that number.
50/30/20 budgeting only works on real money, so start with the amount you can actually spend. Check two consecutive pay stubs in case overtime or bonuses make them differ.
2. The 50/30/20 Budgeting Split, Explained in Plain Numbers
Fifty percent covers needs, thirty covers wants, twenty goes to savings and debt payoff. On a $3,000 monthly take-home, that is $1,500 for rent, groceries, and bills, $900 for fun, and $600 for your future. I taped these three numbers to my fridge the first month because seeing them daily kept me honest. The beauty is the math never changes, only the dollar amounts do.
When my income later rose to $3,600, the buckets grew automatically, which felt like a raise in three places at once. That is why this system outlasts every complicated spreadsheet I ever built.
3. Needs Get 50 Percent, and Needs Means Needs
Define needs as the true non-negotiables: rent, utilities, groceries, transport to work, insurance, and minimum debt payments. Everything else is auditioning for the wants bucket, including the expensive version of a need. A phone is a need; the $95 premium plan is a want in disguise. I cut my needs spending by $180 a month just by downgrading three “needs” that were really wants.
Be ruthless here, because every dollar miscategorized steals from your future. Run through your bank statement and label each charge honestly, even the ones that sting.
4. Wants Get 30 Percent, Guilt-Free
The wants bucket is the reason this system survives past February. Coffee with friends, streaming, hobbies, the occasional impulse buy, all of it lives here with zero shame. I used to feel guilty about every fun purchase, which led to secret spending sprees that wrecked my budget. Now I spend my full 30 percent happily and stop when it is gone.
A budget without joy is a budget you will abandon. The 30 percent is not a failure of discipline, it is the pressure valve that keeps the whole system working.
5. Savings Get 20 Percent Before You Touch Anything
Pay yourself first is a cliché because it works. The 20 percent leaves your checking account on payday, before rent, before groceries, before anything tempting. I set up an automatic transfer for the morning after payday and stopped relying on my willpower entirely. What you never see, you never miss.
After a year, that invisible money became a four-figure emergency fund I was weirdly proud of. Start with 10 percent if 20 feels impossible, then raise it one point every two months. The habit of paying yourself first matters more than the exact percentage in year one. Momentum beats perfection.
6. Automate the 20 Percent on Payday Morning
Automation is the entire secret. Log into your bank, schedule a recurring transfer to savings for the day after each payday, and never think about it again. My bank lets me split direct deposit, so the 20 percent never even touches my checking account. I have missed exactly zero transfers in two years, which is a perfect record my willpower could never match.
Set it once, then live your life. If your employer allows multiple direct deposits, send the savings slice straight to a separate bank so you cannot “borrow” it back impulsively.
7. Track Spending for One Month Without Judging It
For thirty days, write down every dollar you spend. Do not change anything, do not feel guilty, just observe like a scientist studying a strange animal. I discovered I was spending $210 a month on food delivery, a number that genuinely shocked me. You cannot fix what you cannot see, and one honest month of data beats a year of guessing.
Your banking app probably categorizes it all for free, so this takes ten minutes a week. The goal is awareness, not punishment. I found my leaks were all convenience spending, which meant they were fixable without any real sacrifice.
8. Fix the Biggest Leak First, Ignore the Rest
Do not try to fix twelve spending habits at once. Find your single biggest unnecessary expense and attack only that for one month. Mine was food delivery, and cooking four extra dinners a week saved me $160 monthly without touching anything else. Small wins compound into confidence, and confidence is what keeps you budgeting.
One leak fixed beats ten leaks worried about. Once the biggest leak is patched, move to the next one and repeat the process. By month three, I had fixed my top three leaks and freed up $340 a month without feeling deprived at all.
9. Give Every Dollar of the 50 Percent a Job
Even the needs bucket needs a plan, or it quietly overflows. List your fixed costs, then assign what is left to groceries, transport, and household basics with real numbers. I give groceries a hard $320 cap and treat going over like a fire alarm. Without assigned jobs, “needs” becomes a black hole that swallows the wants money too.
Specific beats vague every single time. Write the numbers down where you will see them, because memory is a terrible budget. When every dollar has a job, there is no mystery about where the money went at month end.
10. Build a One-Month Buffer Before You Invest a Cent
Before brokerage accounts and retirement dreams, save one full month of expenses in plain savings. This buffer means a surprise car repair never touches a credit card, which is how most debt spirals start. I built mine with $150 monthly transfers and it took eleven months, slow but steady.
Investing while one emergency away from debt is like building a roof before walls. Once the buffer exists, every future emergency becomes an errand instead of a crisis. Keep it in a separate savings account so it does not blend into spending money. Out of sight really is out of mind.
11. Adjust the Split When Rent Eats More Than Half
Admittedly, the 50/30/20 split assumes reasonable housing costs, which is adorable if you live in a big city. When rent alone hits 55 percent, do not abandon the system, reshape it. Try 60/20/20 or even 65/20/15 temporarily while you work on the housing side. I ran 60/25/15 for a year in an expensive apartment and still made progress.
Just make the adjustment deliberately instead of letting lifestyle creep make it for you. Write down your modified split and revisit it when your housing situation changes. A system you adapt is a system you keep.
12. Use Sinking Funds for Big Predictable Bills
Car insurance, holiday gifts, and annual subscriptions are not surprises, they are just infrequent. Divide each by twelve and save that slice monthly in a labeled savings bucket. My $900 car insurance became $75 a month, and the bill arriving felt like nothing. Without sinking funds, these “surprise” bills land on credit cards and restart the debt cycle.
Predictable expenses deserve a plan. Most banking apps let you create free labeled sub-accounts in about two minutes. I have six sinking funds now, and December stopped being a financial ambush years ago.
13. Review Your Split Every Three Months
Set a calendar reminder for a fifteen-minute money date with yourself every quarter. Check whether the percentages still match your life, because raises, moves, and new bills change the math. I caught my wants creeping to 38 percent during one review and fixed it before it became a habit. A budget you never revisit slowly turns into a decoration.
Quarterly keeps it alive. Bring coffee, keep it short, and end by adjusting one number for the next quarter. I do mine on the first Sunday of each quarter, and it takes less time than scrolling my phone.
14. Forgive the Bad Months and Restart Fast
You will blow the budget some months. A wedding, a car repair, a weak moment with a sale email, life happens to everyone. The difference between people who succeed and people who quit is one thing: the restart speed. I once overspent by $400 in December and was back on track by January 5th because I refused to let shame win.
One bad month is data, not a verdict. The people who win at budgeting are not the ones who never slip, they are the ones who never slip and keep going anyway.
FAQs
Does 50/30/20 budgeting work if my income changes every month?
Yes, with one tweak. Run the percentages on your lowest typical month, then treat anything above that as bonus savings. Freelancers I know do this and it removes the feast-or-famine panic. The percentages stay the same, only the dollar targets move.
What counts as a need versus a want?
Needs keep you alive and employed: rent, utilities, groceries, transport to work, minimum debt payments, insurance. Everything else is a want, including the fancy version of a need. A basic phone plan is a need. The $90 unlimited-everything plan is a want wearing a costume.
Should I pay off debt or save first with the 20 percent?
Split it while high-interest debt exists. Throw most of the 20 percent at anything over 10 percent interest, and keep a small slice building a starter emergency fund. Once the expensive debt is gone, the full 20 percent goes to savings and investing.
Is 20 percent savings realistic on a small salary?
It is a target, not a pass-fail test. If 20 percent is impossible right now, start at 10 and raise it one point every few months. The habit of paying yourself first matters more than the exact percentage in year one.
How do I handle months with big irregular bills?
That is what sinking funds are for. Divide each annual bill by twelve and save that slice monthly in the needs bucket. When the car insurance bill lands, the money is already sitting there and your month does not explode.
Conclusion
My first year of real paychecks taught me that budgeting is not about restriction, it is about giving every dollar a job before it disappears. The 50/30/20 split made that automatic for me, and it can do the same for you. Which bucket will you fund first this month?