My husband and I retired within a year of each other, and for the first time in forty years, no paycheck was coming. Our fixed income — Social Security plus a modest pension — totaled about $3,600 a month. Then the water heater died ($1,200) and the car needed brakes ($700). We had retirement savings, but raiding them for every surprise felt wrong. So we built a separate cushion, slowly and cheaply.
Why Retirees Need an Emergency Fund Too
There is a myth that emergency funds are for young workers and retirees can just pull from savings. But every unplanned withdrawal costs: taxes, lost growth, and the sting of a shrinking nest egg. A dedicated fund protects retirement savings from everyday life.
Retirees have advantages: no commuting costs, time to comparison shop, decades of resourcefulness. These ideas are designed for fixed incomes. Slow, steady, completely doable.
- Handle surprises from a separate fund, not retirement
- Three months of essentials is a fine target
- Small automatic transfers beat occasional large ones
- Replenish after every use — a cycle, not a project
1. Set a Realistic Target: Three Months of Essentials
Forget generic “six months of expenses” advice. Our essentials — housing, food, insurance, medications, utilities — ran about $2,400 a month. Three months meant $7,200, achievable in a way $14,000 never was. We settled on $5,000 as our working cushion.
A realistic target you can reach beats an ideal one you abandon. Calculate true essentials — must-pays only — and multiply by three. Ours took fourteen months, and every month the growing balance kept us going.
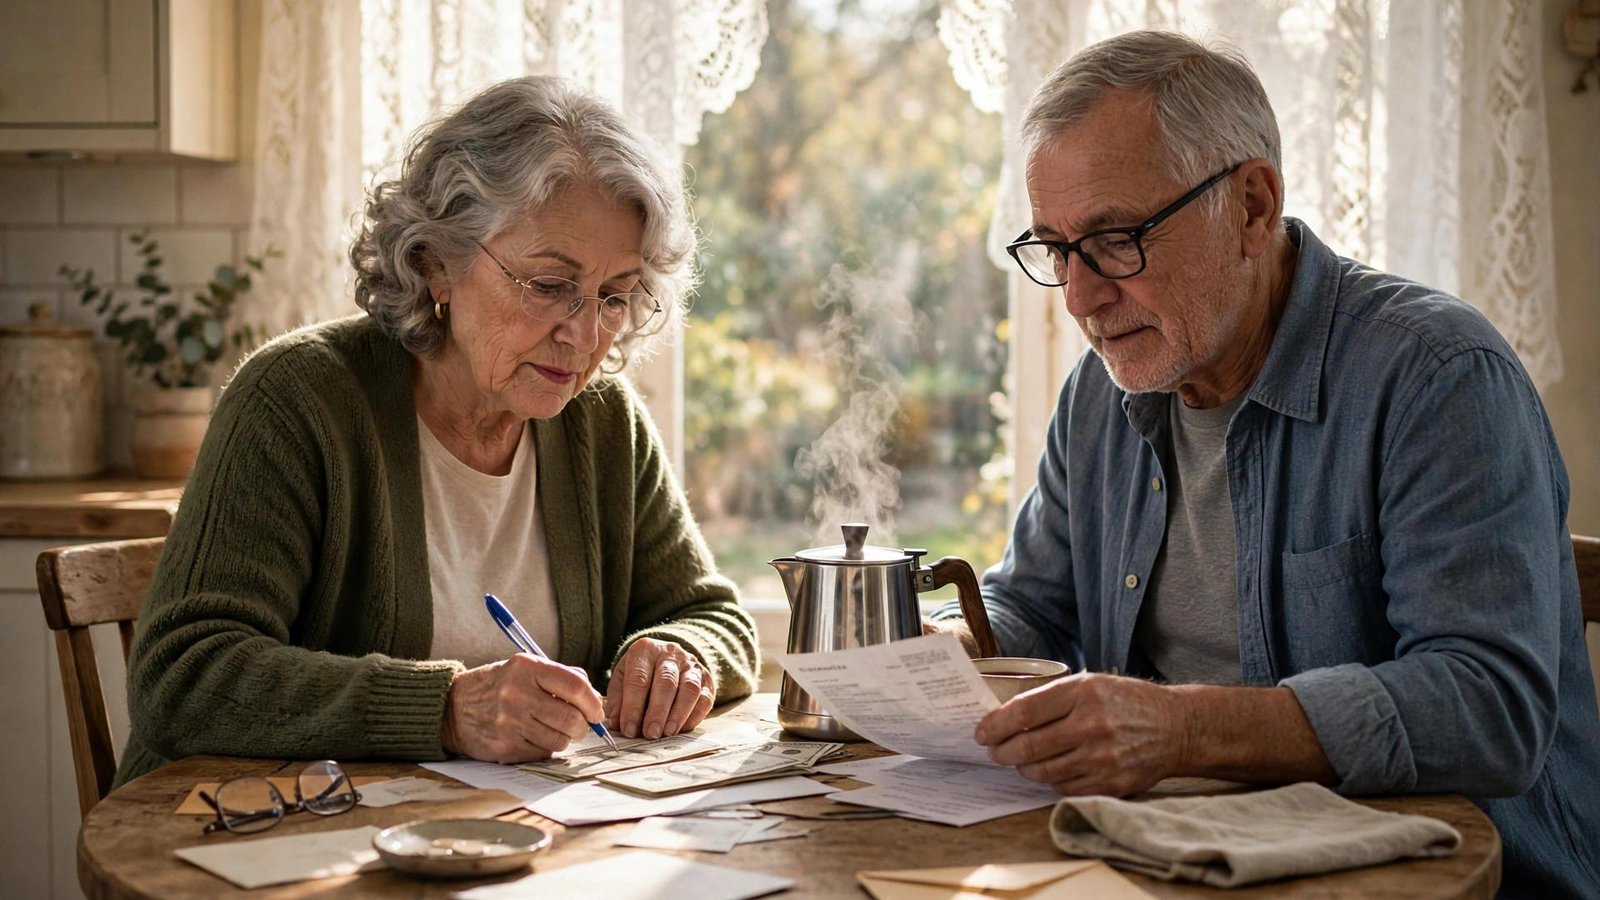
2. A Retired Couple Reviewing Bills Together at the Table
Our first step: sit down with every bill and ask, does this still make sense? We found a $60 cable package we barely watched, an unused gym membership, and duplicate streaming services. Cutting them freed $130 a month.
That $130 went straight into the emergency fund automatically — never seen, never missed. One Saturday morning and a pot of coffee funded our savings for the entire first year. Your spending patterns changed at retirement even if your bills did not.
3. The “Paycheck Split” on Fixed Income
We treated our fixed income like a paycheck with a split: when the Social Security deposit landed, $200 moved to the emergency fund before anything else. Fixed income makes this easier — the amount never changes, so the transfer never needs adjusting.
Automating on fixed income is beautifully boring. Same amount, same day, every month, zero decisions. After a year: $2,400 without a single moment of willpower. The money never felt like ours to spend.
4. Downsize One Recurring Cost at a Time
We attacked recurring costs gradually. First the cable, then car insurance shopped for a $35 monthly saving, then a cheaper phone plan saving $40. Each cut was small; together they freed over $200 a month.
One call or switch per week, no marathons. Every freed dollar went to the fund, so lifestyle never inflated to absorb the savings. A year later our costs were permanently lower and our cushion permanently bigger. Slow beats heroic.
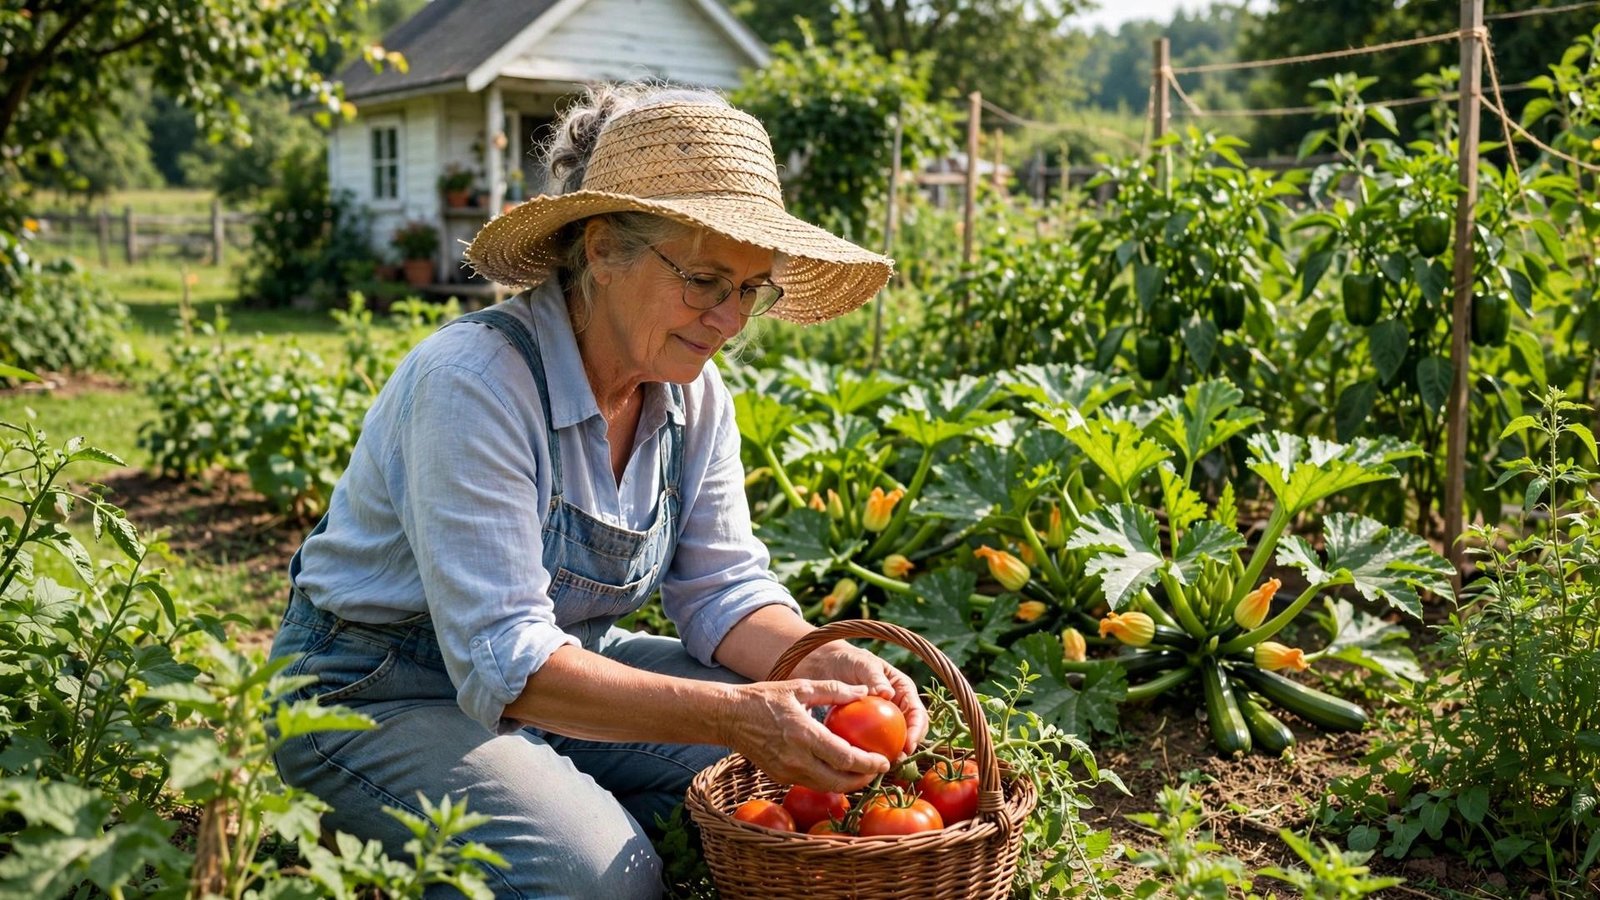
5. A Garden Full of Vegetables Behind a Small House
We turned a sunny yard patch into a vegetable garden, cutting summer grocery bills nearly in half. Tomatoes, zucchini, peppers, herbs — about $80 a month for four months, all straight into the emergency fund.
Gardening saves money twice: cheaper groceries, and mornings in the garden instead of mornings at the shops. Surplus went to neighbors, which bought goodwill no fund can measure.
6. Sell What the Big House No Longer Needs
Retirement was our excuse to clear decades of accumulation. Furniture, tools, boxes untouched for years — sold online and at one big yard sale. Total: just over $1,800, every cent seeding the fund.
Decluttering for cash is the rare win-win: a simpler home, a fatter cushion. We were ruthless about anything unused in two years. The money felt like found money — easy to save, not spend.
7. The Senior Discount Audit
We made a game of asking for senior discounts — restaurants, pharmacies, insurance, internet. Most places offer 10 to 15 percent if you ask, and we had left that money on the table for years. Total: around $60 a month.
Awkward the first two times, then habit. Keep a fridge list of who gives what. Sixty dollars a month is $720 a year into the fund, earned with nothing but the courage to ask.
8. Two People Cooking a Big Pot of Soup in a Cozy Kitchen
With more time at home, we leaned into cooking from scratch — food spending dropped from $600 to about $380 a month. Big pots of soup, beans, roasted vegetables, homemade bread. The savings were $220 monthly, and honestly the food got better.
Cooking together became a highlight of our week. One new recipe every Sunday kept it fun, not frugal-feeling. Restaurant meals became a monthly treat instead of a weekly habit — more enjoyable too. The kitchen paid for our peace of mind.
9. Keep the Fund in a High-Yield Savings Account
Our fund sits in a high-yield account earning around 4 percent, separate from checking. Safe, a little growth, and — crucially — a day or two to transfer out, which stops impulse raids. Accessible in a real emergency, annoying to reach on a whim.
Separation is the strategy. Money mixed with daily spending gets spent; money in its own account gets saved. We named it “Emergencies Only,” and that label has stopped more than one questionable withdrawal.
10. The “One In, One Out” Spending Rule
Anything new in means something old out — and the difference goes to the fund. New jacket? An old one gets donated, the sale savings go to savings. It ended the slow accumulation of stuff that used to drain us.
The rule forces a pause: do I want this enough to give something up? Half the time the answer was no, and the unspent money went to the fund. Closets stopped growing; the cushion kept growing.
11. A Couple Walking Their Dog Past a “For Sale” Sign They Ignore
Friends kept upsizing — bigger trips, newer cars, renovated kitchens — and the pressure to keep up was real. We consciously opted out. Our paid-off car, modest home, and simple routines were not deprivation; they were why we slept at night.
Comparison is the enemy of a fixed-income budget. Every dollar not spent keeping up is a dollar of safety. Opting out was not a sacrifice — it was a relief. Our walks got longer, our worries shorter.
12. Use Windfalls Wisely: Half to the Fund
Tax refunds, birthday checks, a small inheritance — windfalls still happen in retirement. Our rule: half to the fund, half ours to enjoy. A $900 refund became $450 of security and $450 guilt-free.
Windfalls are when savings plans usually die. Without a rule, the whole refund becomes a television. With the rule, you get progress and enjoyment — which means you actually follow it. Fair splits are sustainable splits.
13. Review Insurance Once a Year
Every year we shopped homeowners and auto insurance together. Loyalty was costing us — quoting competitors and asking our insurer to match saved $400 to $600 yearly. One afternoon, a little paperwork.
Insurance quietly inflates if never checked. Put a yearly reminder on the calendar. The savings go straight to the fund, and the coverage is just as good — sometimes better.
14. Replenish Immediately After Using It
When the water heater died, we spent $1,200 — and the next month doubled our automatic transfer until the fund was whole again. A fund that is not replenished is just a slow leak. The refill plan starts the day you spend from it.
This separates people who have a fund once from people who have one forever. Emergencies will keep happening; that is the point. Every withdrawal triggers a refill plan, automatically, without debate.
The Mistake We Almost Made
Early on we were tempted to invest the fund “so it would grow faster.” Six months later we needed $2,000 for a roof repair while the market was down 12 percent. Selling at a loss to fix a roof — worst of both worlds.
Emergency money has one job: being there, in full, when needed. Growth is for retirement accounts. Keep the fund safe, liquid, and boring. Boring is the entire point.
A Simple Retiree Emergency Plan
$200 automatic transfer on the first of every month into a separate high-yield account. Target $5,000. True surprises only. After any use, double the transfer until refilled. Review yearly.
Write it down, both sign it, stick it where you will see it. A plan explainable in thirty seconds is a plan you will follow.
Conclusion
Fourteen months after that dead water heater, we had our $5,000 cushion, retirement savings untouched, and a monthly budget that finally felt calm. Fixed income did not stop us — it just meant building security one deliberate dollar at a time.