I am a freelance designer: some months $6,000, some months $1,800, never knowing which is coming. For two years I carried $11,000 in credit card debt because every payoff plan assumed a steady paycheck I did not have. The month I got serious, I built a system designed for irregular income instead of fighting it. Eighteen months later, the debt was gone.
Why Standard Debt Advice Fails Freelancers
Almost all debt advice assumes the same paycheck on the same day, every time. “Pay $500 a month toward your highest-interest debt” is great for salaries. For the rest of us, a $500 promise is one we cannot always keep — and broken promises to yourself kill debt plans.
The fix: build around your worst month, not your average. Use lean months as the baseline and treat good months as bonus attacks. Slower on paper, faster in real life — because you can actually keep it.
- Base commitments on your worst month, not your average
- Good months are for debt attacks, never lifestyle upgrades
- Minimum payments are sacred and automatic, every month
- Track the total monthly — watching it fall is your fuel
1. The Baseline Budget: Plan for Your Worst Month
I checked twelve months of income and found my worst: $1,900. I built the whole budget — rent, bills, food, minimums — inside $1,900. Everything above that in a good month was surplus with one job: attack debt. Never missed a payment, even in lean months.
Planning for the worst is liberating. A $1,900 month brings no panic — the plan covers it. A $5,000 month feels like a windfall, easy to throw at debt.
2. A Freelancer Splitting a Big Invoice Payment Into Piles
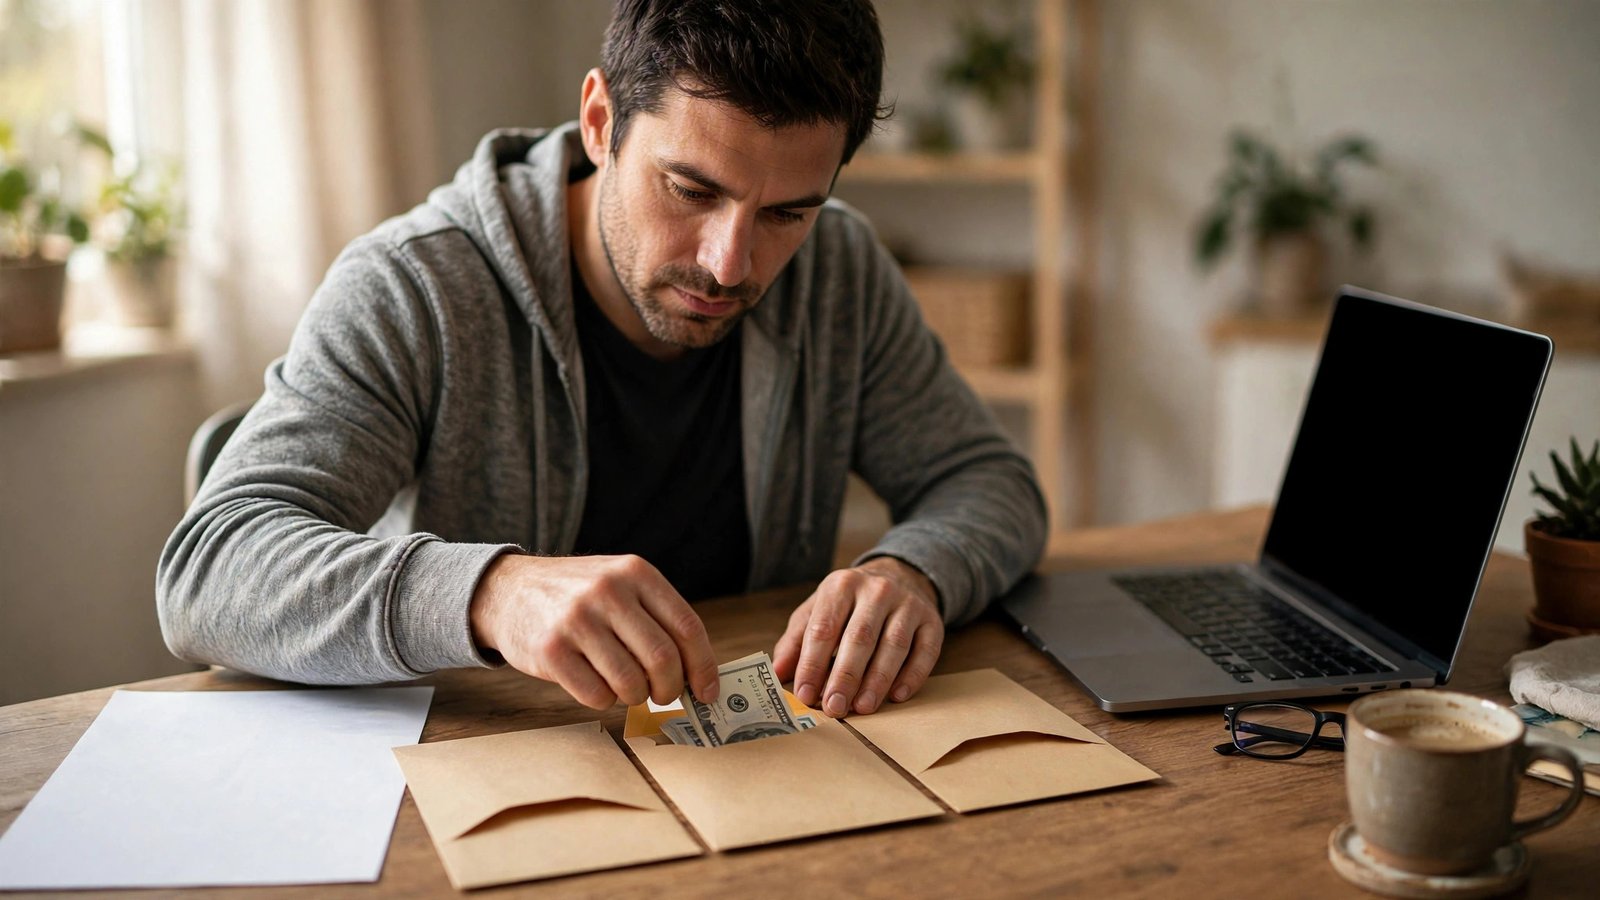
When a big client payment landed — say $4,200 — I split it the same day: taxes, bills, minimums, debt-attack pile. Immediately, before the money could feel like “extra.” The attack pile went straight to the highest-interest card that afternoon.
Speed matters because money sitting in checking evaporates. Same-day splitting turned every good invoice into a debt payment before lifestyle creep claimed it. Those attacks were more than half of my total payoff.
3. Automate Minimums, Attack Manually
Every minimum was on autopay, timed after my most reliable client paid — the untouchable floor. Extras were manual, made on good days when the surplus was visible. I wanted to feel each one leave; that made progress real.
4. The Debt Avalanche, Adjusted for Chaos
The avalanche — attack the highest-interest debt first — still works with irregular income. I listed debts by rate and aimed every surplus dollar at the 24 percent card while others got minimums. When it died, its payment rolled to the next.
The adjustment: the attack amount changes monthly, and that is fine. Some months $800, some $60. The direction never changed, only the speed. Consistency of direction beats consistency of amount.
5. A Wall Chart Tracking a Shrinking Debt Balance
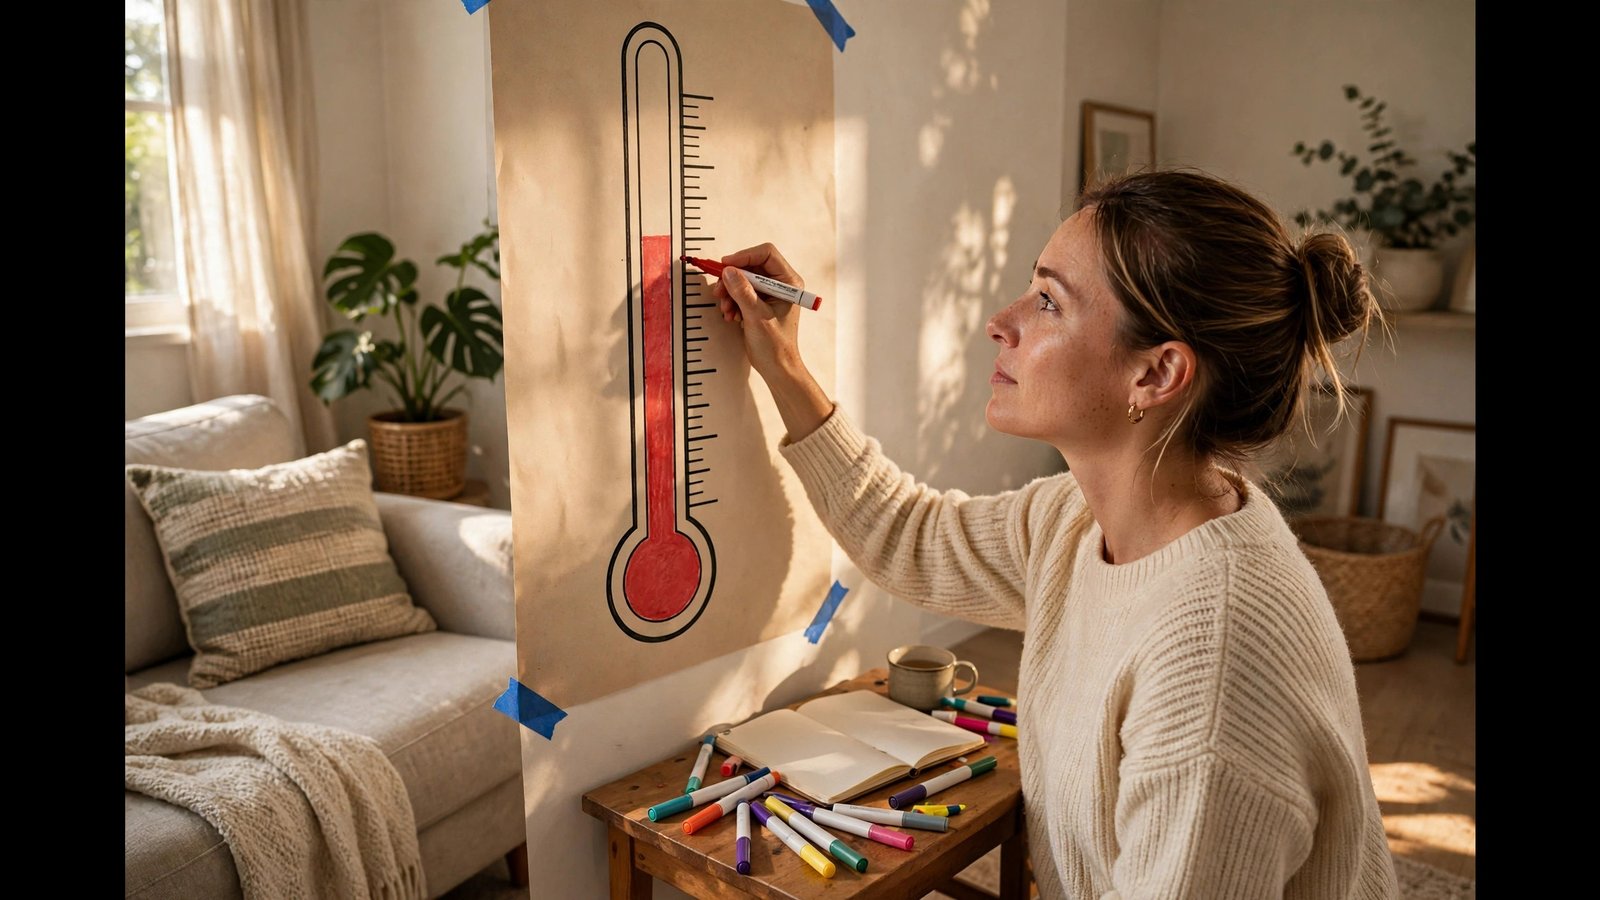
I drew a giant thermometer on poster board: $11,000 at top, zero at bottom. Every payment, I colored in progress. Embarrassingly low-tech, unbelievably motivating. Watching that line climb kept me going through thin months.
Visible progress is fuel when the finish line keeps moving. I wrote each payment’s date next to the line — a record of persistence. The day I colored the last section, I took a photo. It is still on my phone.
6. The “Half of Every Windfall” Rule
Tax refunds, bonuses, a client paying late all at once — windfalls are dangerous. My rule: half to debt immediately, half mine to enjoy or save. A $1,200 refund became a $600 attack and $600 guilt-free. Fair, so I actually followed it.
Windfalls are where debt plans accelerate or die of lifestyle inflation. The 50/50 split gives you progress and a life. Without the rule, the whole refund becomes a television.
7. Separate Your Tax Money or Regret It
Non-optional for freelancers: I moved 25 percent of every payment into a separate tax account the day it arrived. Before this, I “borrowed” tax money for debt, then put the tax bill on a credit card at crunch time — creating new debt while killing old.
Untouchable tax money is a prerequisite for any irregular-income debt plan. Name the account “Taxes — Do Not Touch” and automate it. Paying the IRS with a credit card is the most expensive freelancer mistake there is.
8. A Person Calling a Creditor to Negotiate a Lower Rate
I called all three card companies and asked for lower rates. Two said yes: 24 to 18 percent, 22 to 19. Fifteen minutes each, hundreds saved. My line: “I am considering a balance transfer — what can you do?”
Creditors would rather keep you at a lower rate than lose you, but they never offer — you ask. If the first rep says no, escalate. Yearly, for every card with a balance. The highest-paid fifteen minutes in personal finance.
9. The “No New Debt” Freeze
While paying off debt, the cards went in a drawer and I spent only from checking. Non-negotiable: adding new debt while paying old is bailing water with a hole in the boat. The freeze lasted the full eighteen months.
The freeze taught me my real spending. Without the card buffer, every purchase came from visible money, and spending dropped naturally — freeing more for payoff. The cards are back now, paid in full monthly. But I needed the freeze to get here.
10. Build a Tiny Buffer Before Attacking
Before throwing everything at debt, I saved a $1,000 mini emergency fund. It felt backwards at 24 percent interest — but without a buffer, every surprise went back on the card, undoing progress. The buffer broke the cycle.
It got used twice: a car repair, a slow client month. Both times I paid cash instead of adding to cards. That $1,000 probably prevented $3,000 in new debt. Defense first, then offense.
11. Stacks of Paid-Off Statements in a Folder
I kept every payoff confirmation in a physical folder, each paid-off card’s final statement marked with a big red “DONE.” Flipping through it on hard days showed me how far I had come.
Debt payoff is delayed gratification, and your brain needs milestones. The folder made progress tangible in a way numbers on a screen never did. When friends ask how I did it, I hand them the folder and let the stack talk.
12. The Side-Gig Sprint (Temporary and Targeted)
For three months I took extra projects with one rule: every dollar to debt. Exhausting, but as a sprint it killed nearly $3,000. Temporary intensity beats permanent burnout, and an end date made it bearable.
Targeted is the key word. Sprint income drifting into general spending is extra work for nothing. I kept it in a separate account and transferred it to debt the day it cleared. Three months, then back to normal life.
13. Refinance or Consolidate When It Makes Sense
Halfway through, I moved the highest-interest balance to a 0 percent transfer card with a 3 percent fee. Every payment attacked principal — roughly $600 saved, payoff noticeably faster.
Transfers only work if you add no new spending and clear it before the promo ends. Read the terms, set a month-eleven reminder, treat the deadline as sacred. Used correctly it is free money; used carelessly it is a trap.
14. Celebrate Milestones Without Spending Money
Every $2,000 killed, I celebrated free: a day hike, a long bath with a library book, a favorite home-cooked meal. Marking progress matters, but celebrating with spending is self-sabotage.
Unacknowledged progress leads to quitting. I told a friend about each milestone, which made it real. Find someone who cheers your $8,000-to-$6,000 moment — that is exactly when most people give up.
The Mistake That Extended My Debt by Six Months
My worst error: “borrowing” tax savings for bigger debt payments. The balance dropped faster — until April, when I owed $2,800 I had spent. It went on a card at 22 percent, costing me six months.
Never rob earmarked money to pay debt faster. Tax money, rent money, emergency funds are walls, not suggestions. The fastest plan creates no new debt along the way.
A Simple Irregular-Income Debt Tracker
One page: each debt with balance and rate, total at top, updated monthly. Below, this month’s attack amount based on what actually came in. Five minutes, total clarity.
The monthly total is what matters. Mine went $11,000, $10,400, $9,100, $8,800 — never straight, always falling. On flat months the tracker reminded me: standing still is not sliding backward.
Conclusion
Eighteen months after I stopped fighting my irregular income and started planning around it, the $11,000 was gone. A wall chart, a folder of statements, a lot of same-day transfers — not elegant, but built for my real life. That is why it worked.