When my marriage ended, I became a single mom of two on $2,800 a month, and the math did not work. Rent alone was $1,100. For months I paid whatever screamed loudest and hoped the rest would sort itself out. It did not. The turning point was a Tuesday night at my kitchen table when I realized hope is not a financial plan — and I built one instead.
Why Saving Feels Impossible on One Income
Two-income households have a cushion. Single parents do not. Every expense lands on the same paycheck, with no backup when the car breaks the same week the kids need shoes. The margin for error is zero.
But single parents are the best budgeters on earth — necessity is the best teacher. These strategies are not about deprivation. They make one income do the work of two by being deliberate with every dollar.
- Kids’ needs first, but “needs” is smaller than guilt says
- Save something monthly, even just $25
- Free and cheap fun counts as real fun
- Claim benefits and programs — that is what they are for
1. The “Bills First” Payday Routine
On payday, before anything else, I pay every bill due before the next check: rent, utilities, insurance, phone. What is left is the real budget — I plan two weeks around that number, not the fantasy of my full paycheck.
This ended the robbing-Peter cycle. No mid-month panic, no late fees. Twenty minutes on payday morning buys two weeks of peace. My kids noticed before I did — mom stopped stressing about money by the 20th.
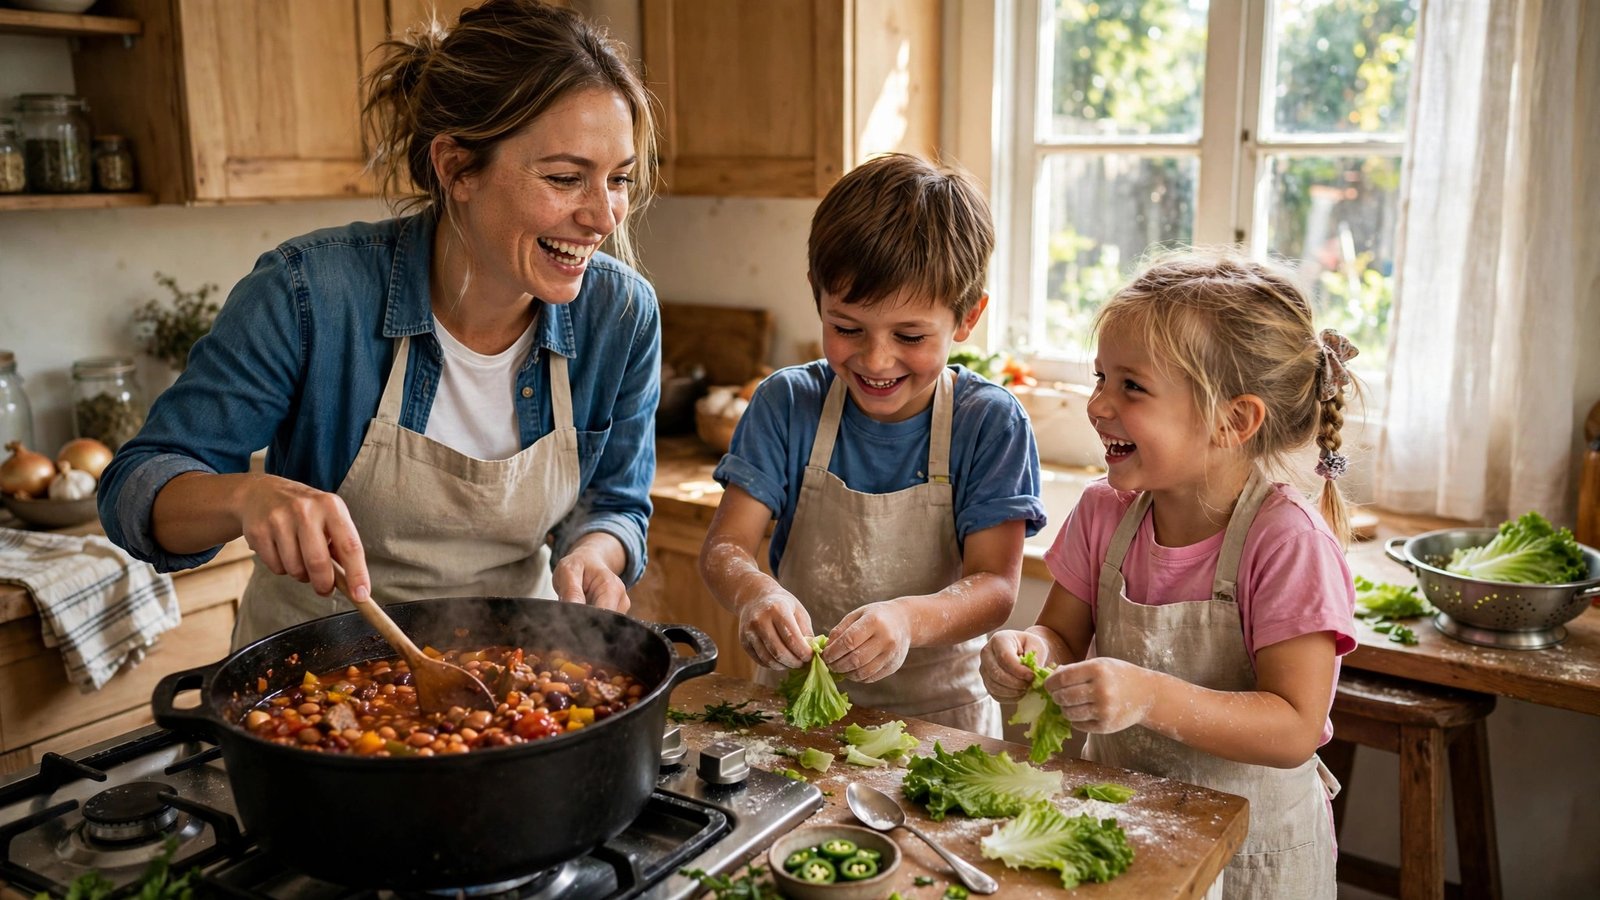
2. A Parent and Kids Cooking a Big Batch Meal Together
Feeding three people meant cooking became non-negotiable. Every Sunday, my kids and I batch-cooked something — chili, pasta sauce, soup — covering dinners for the week. Groceries settled around $450 a month for all three, down from $700 winging it.
The kids loved it: stirring, tearing lettuce, setting the table — it became our thing. Batch cooking also killed the 6 PM panic that ended in pizza delivery. One Sunday hour saved hundreds monthly.
3. Claim Every Benefit You Qualify For
Pride kept me from applying for assistance for six months — pride that cost real money. When I finally applied, we got reduced school lunches, utility assistance, and a childcare subsidy nearly halving daycare. These programs exist for families like mine.
Start with your state’s benefits site and the school counselor, who knows every local program. One afternoon of paperwork unlocked $300-plus a month. That is a bridge, and there is zero shame in using it.
4. The $25 Automatic Savings Transfer
Twenty-five dollars a month sounds like nothing, and that is why it works. I set up an automatic $25 transfer every payday. Small enough to never miss, never cancel. After a year: $600 plus interest — my first real cushion.
Small automatic savings beat big ambitious savings that never happen. Once the habit locked in, I raised it to $40, then $50. The amount matters less than the automation, because willpower fails and transfers do not.
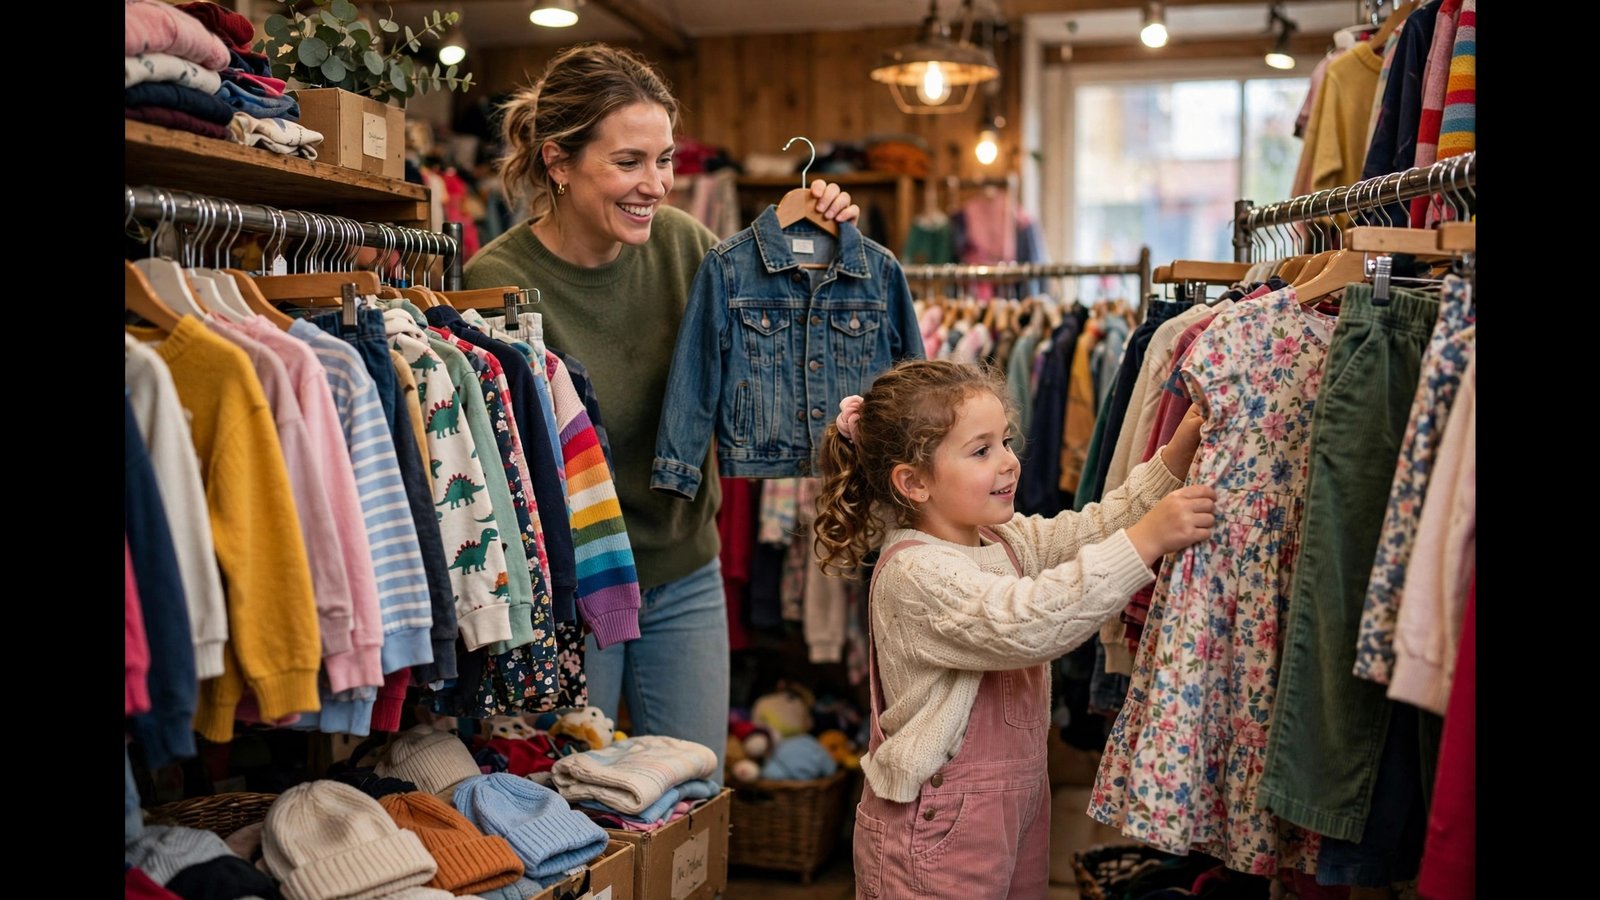
5. A Secondhand Store Rack Full of Kids Clothes
Kids outgrow clothes faster than budgets keep up. I stopped buying new entirely and switched to thrift and consignment. A full seasonal wardrobe for both kids cost under $100, versus $300-plus at regular stores.
My kids did not care — they liked the treasure hunt. I also joined a parents’ swap group for free trades. Clothing went from budget-buster to rounding error, and the kids learned that secondhand is just smart.
6. Meal Plan Around the Grocery Sales
I flipped the usual order: check the weekly ads first, then plan meals around what is cheap. Chicken on sale became chicken week. Marked-down turkey meant tacos and pasta sauce. This cut grocery spending about 20 percent with zero extra effort.
I kept ten cheap family meals in rotation and matched them to the sales. The kids never noticed the pattern, and I stopped paying full price for anything. Sale-based planning turns shopping into a small weekly victory.
7. The Library as Your Free Entertainment Center
The library saved my entertainment budget: free books, movies, kids’ programs, even museum passes. Our weekends cost almost nothing, and the kids’ summer reading program replaced hundreds of dollars in activities.
Saturday library trips became a ritual — new books, a family movie, whatever free event was on. The kids looked forward to it like any paid outing. When money is tight, free does not mean lesser. It means smarter.
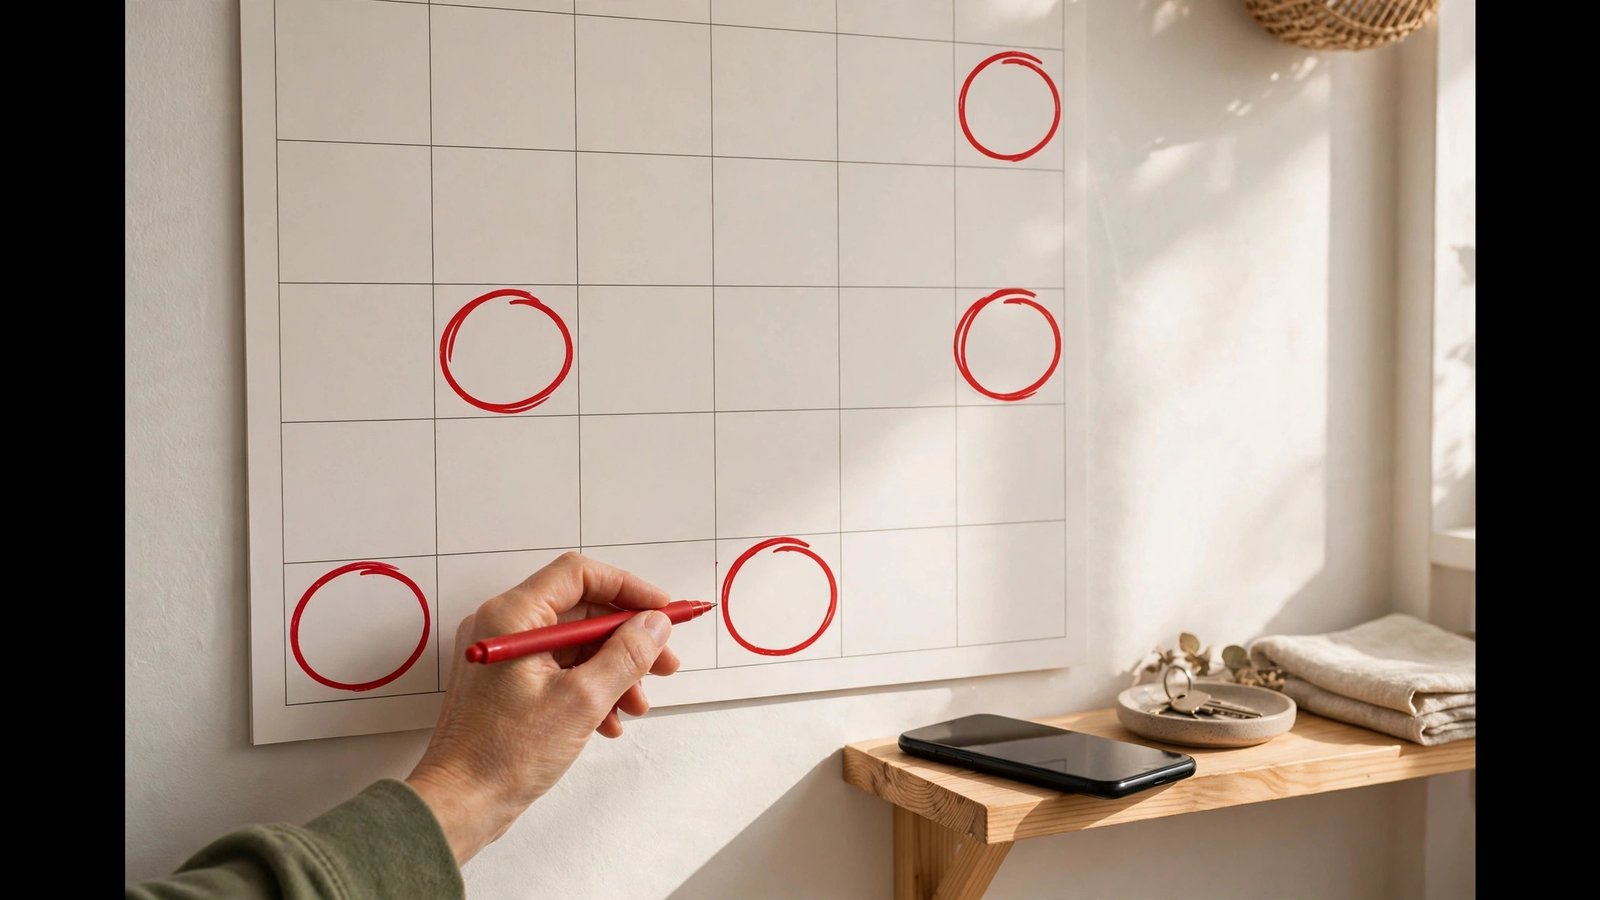
8. A Calendar With Bill Due Dates Circled in Red
Late fees were bleeding me dry — $30 here, $25 there, over $100 some months. I bought a wall calendar, wrote every due date in red, and set phone reminders three days ahead. Late fees hit zero within two months.
The calendar hung where I saw it every morning, making due dates impossible to ignore. I also asked two companies to move due dates to right after payday — both said yes. Organized bills are paid bills, and paid-on-time bills keep money in your pocket.
9. Cook Once, Eat Twice (at Least)
Every dinner was planned for leftovers. Roast chicken became tacos, then soup. A pot of beans became burritos, then chili. Cooking double cost barely more but eliminated whole meals I would have had to figure out — or order in.
This is the highest-return habit in my kitchen. It halves the nights I think about dinner and doubles every grocery dollar. My rule: if the oven is on, something extra goes in. Future me is always grateful.
10. The “Cash for Fun” Envelope
I gave us $60 a month in cash for fun. Envelope empty, fun spending stops. Cash made the limit physical in a way a budget line never could — the kids even checked the envelope before asking for treats. Budgeting without a single lecture.
Sixty dollars covered ice cream outings, a thrift-store toy, movie night. A defined fun budget meant yes sometimes without guilt, no the rest of the time without drama. Boundaries are a gift to kids too.
11. A Piggy Bank Filling With Coins on a Kitchen Counter
I started saving every coin and small bill from my purse and pockets in a jar on the counter. The kids loved feeding it. Every three months it held $80 to $120 — money that would otherwise have vanished into vending machines.
The jar captured money already “spent” in my mind. I never missed it, but it added up. The kids started their own jars too. Small money, big lessons.
12. Negotiate the Bills You Think Are Fixed
One afternoon I called my internet provider, phone company, and car insurance agent and asked for lower rates. Internet dropped $20, phone $15, and a competitor’s insurance quote saved $30. Forty-five minutes of awkward calls: $65 a month back.
Almost every recurring bill is negotiable. The magic sentence: “I am thinking of switching — is there anything you can do?” Do this yearly. It is like giving yourself a raise.
13. Side Income in the Margins of the Day
No time for a second job, but I had margins. I sold outgrown kids’ stuff online, did occasional weekend babysitting, and took one freelance project a month. It added $150 to $300 monthly without wrecking my schedule.
I chose income that fit my life: selling things I owned, skills I had. Every extra dollar went straight to savings, since the budget already covered life on my main income.
14. Teach the Kids the “Want vs. Need” Game
At the store we played want-or-need. The kids got good at it; impulse buys plummeted. It gave them a framework instead of just hearing “we cannot afford it,” which always felt like punishment.
Mine learned that skipping small wants meant bigger yeses, like our annual beach day. Financial literacy started at the grocery store.
The Mistake That Cost Me the Most
My costliest mistake was payday loans. Twice, when the car broke and savings were empty, I borrowed a few hundred and paid hundreds in fees. It felt like the only option, and it made everything worse.
The way out was a tiny emergency fund plus a local credit union with small emergency loans at sane rates. Considering a payday loan? Call a credit union first. Almost anything is cheaper.
A Simple Two-Paycheck Monthly Plan
Payday one covers rent and big fixed bills. Payday two covers groceries, gas, variables. Savings comes out of both automatically, even if small. Fun money is whatever is left — cash, in the envelope.
One page on the fridge. When life gets chaotic, the plan runs on autopilot. Simple survives; complicated collapses.
Conclusion
Three years after that kitchen-table Tuesday: an emergency fund, no payday loan debt, two kids who know a want from a need. One income was enough — not because it grew, but because I finally told every dollar where to go.